This week, two Western industrial camps made the same confession, two days apart, without ever pronouncing the word. The staging, however, spoke of something else: 25,000 Atlas robots promised to Hyundai and Kia factories, a humanoid lifting a washing machine in a single motion, a British startup swearing to become the world number one. A convenient spectacle. Beneath the veneer, a single hard metric runs from one press release to the next, and it does not concern the robot: it concerns its most expensive organ. The actuator, this motorised muscle, accounts for 60% of the material cost of an industrial humanoid on its own. The question of the week is not “who has the best robot”. It is “who owns the engine”.
The only hard metric the week tried to bury
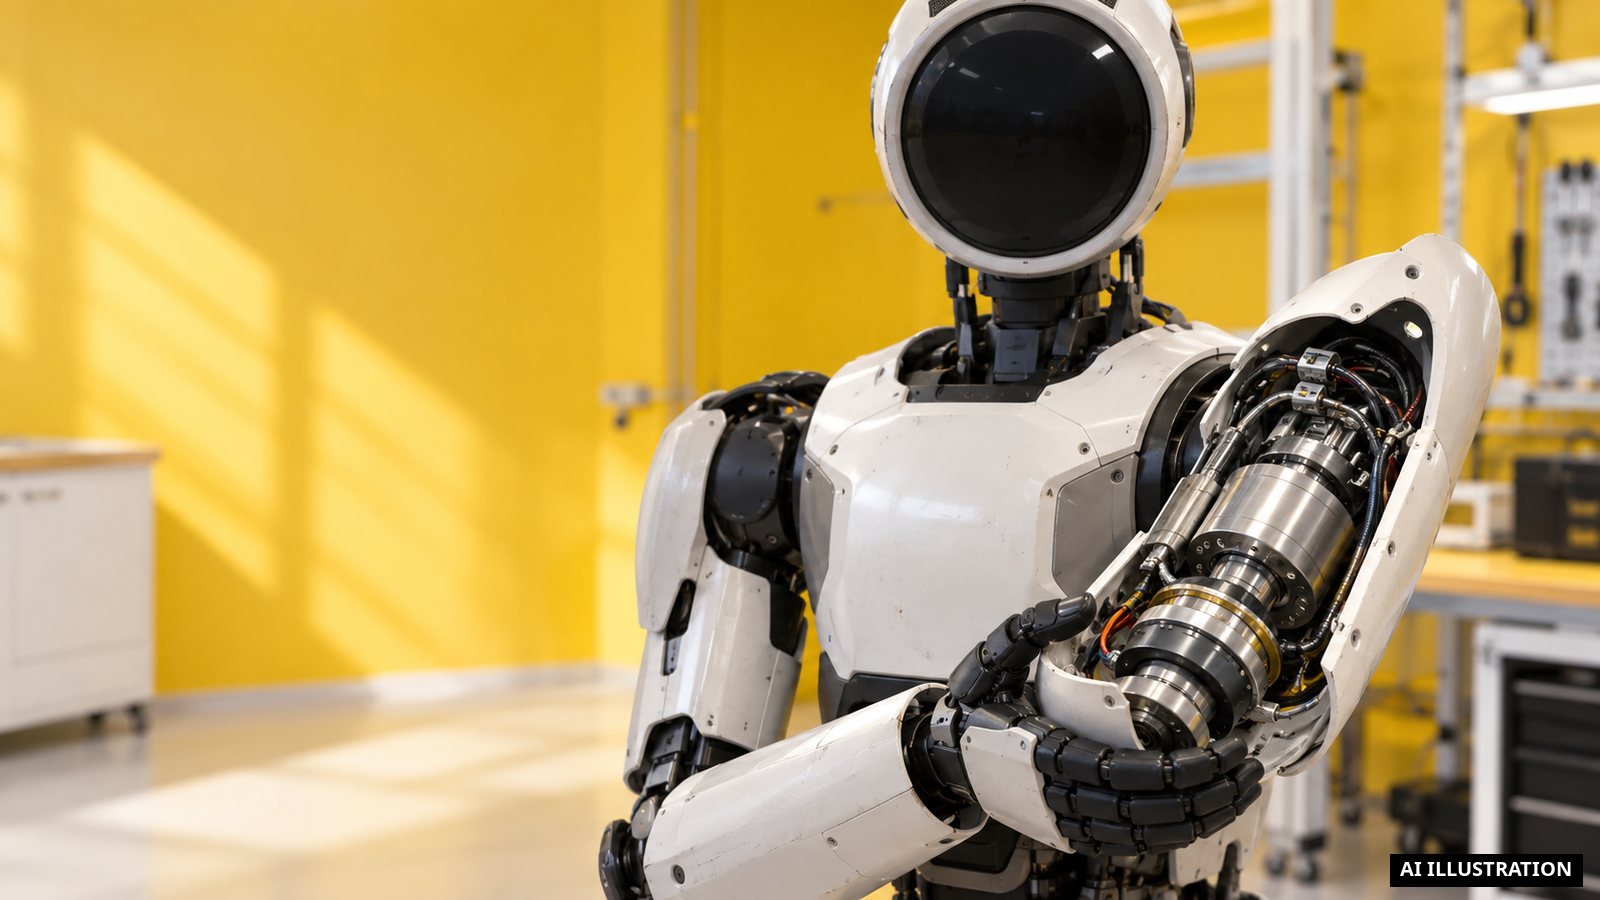
The figure came from Hyundai’s mouth, not from a hostile analyst. In the wake of the announcement on Atlas, the South Korean group detailed its upstream plan: Hyundai Mobis will produce more than 350,000 actuators per year in the United States from 2028, and these actuators represent 60% of the total manufacturing cost of the Atlas robot. The precision was repeated in a second version of the dossier, with a technical detail that says everything about the weight of the organ: each Atlas robot requires more than ten actuators, and this assembly weighs approximately 60% of the material cost. Hyundai Mobis describes these components as the robot’s muscles and plans a dedicated American factory with an annual capacity of 350,000 units from 2028.
Keep the order of magnitude in mind, because the rest of the week follows from it: in a humanoid, what costs is neither the software “brain” nor the bodywork, but the chain of motors that moves the joints. Whoever holds the actuator holds the margin. The robot, for its part, is merely an assembly around this organ.
Hyundai: a single group, from engine to buyer
The visible part of the announcement was tailored for the investor. On 19 May 2026, during a JPMorgan Chase investor session in Boston, Hyundai Motor Group announced the deployment of more than 25,000 Atlas robots, designed by Boston Dynamics, in its Hyundai and Kia automobile factories. The following day, Boston Dynamics published the technical demonstration that serves as a guarantee for the volume: Atlas lifts and tidies away a washing machine by coordinating torso, arms, legs and joints via a single reinforcement learning policy rather than separate modules, this policy adapting to variations in load mass, floor friction, grip force and object position without being modified from one variation to the next. The implicit message: a versatile robot, and therefore deployable in mass.
But the real subject is underneath, and it is one of structure, not of feat. The same group holds the entire chain. It owns the robot via Boston Dynamics. It owns the actuator via Hyundai Mobis and its American factory with 350,000 units per year. And it is its own first customer: Hyundai plans to absorb approximately 83% of its own Atlas production in-house before considering a stock market listing for Boston Dynamics, relying on this captive volume to lower unit costs. The calculation holds to the digit: the 25,000 announced robots represent precisely approximately 83% of the target capacity of 30,000 units per year that the group aims for by 2028.
Customer, robot manufacturer, manufacturer of the most expensive organ, and first captive buyer: everything is in the same hand. Vertical integration is not a by-product of the Hyundai strategy, it is the strategy. The deployment of 25,000 units is not a commercial outlet, it is the shock absorber that makes the actuator profitable before a single robot is sold externally.
Humanoid.ai: the inverted mirror, the same confession
At the other end of the structural spectrum, a British startup does exactly the opposite — and confesses exactly the same thing. Humanoid.ai claims more than 200 engineers and researchers and aims for the position of world number one in industrial humanoid robotics within two years. It has neither a factory nor its own actuator. Its response, the same week, was therefore not to build them, but to secure them by contract.
Two locks, placed on 21 May 2026. First, manufacturing: Humanoid.ai and Robert Bosch GmbH announced a contract manufacturing agreement for the HMND 01 robot, intended for the European industrial market; in this framework, Bosch applies its Design for Excellence standard to the HMND 01 to optimise manufacturability, reliability, maintainability and cost. Then, and this is the decisive lock, the organ: Schaeffler is designated the preferred actuator supplier for the HMND, covering more than 50% of actuator demand until 2031.
Schaeffler is not just the motor supplier: it is also the first deployment site. The initial deployment of the HMND is scheduled from December 2026 to June 2027 at two German sites, Herzogenaurach and Schweinfurt. The Beta version of the HMND carries a payload of 20 kg, i.e. 10 kg per arm, and must be deployed at Schaeffler sites in Germany from the end of 2026. A two-year-old startup declaring itself a candidate for the world title thus begins by securing more than half of its actuators until 2031 and by installing its robots at the supplier of those same actuators.
Two architectures that oppose everything — vertical integration on one side, locked outsourcing on the other — and a single common phrase in the background: without control of the actuator, no robot.
When the automotive supplier descends into the robot
The underlying shift is there. Hyundai Mobis, Bosch, Schaeffler are not roboticists who came to buy motors. They are automotive suppliers who descend into the robot from the bottom, via the organ they already know how to produce in volume: the motor, the actuator, precision mechanics. The humanoid, in this movement, ceases to be a product to become an assembly organised around a motor supplier. It is the supplier of the organ who structures the chain, not the integrator of the robot.
One absent party remains in the downstream part. According to Interact Analysis, Europe should remain marginal in deployments of humanoid robots by 2035, due to stricter labour regulations than in China or the United States. Marginalised on the ground, Europe therefore repositions itself upstream, where Bosch and Schaeffler have a century’s head start: on the organ. Not on the deployed robot, but on the motor that moves it.
From lying about performance to the cold war of the supply chain
This thread has followed this arc for several months, and the week closes it by reversing it. On the Chinese side, we had documented a closed loop: an energy player that finances the AI designer, manufactures the robot, deploys it at its own site, measures its own success rate and awards itself the title — investor, energy supplier, manufacturer and judge in the same hand. That loop relied on the falsification of a performance metric, a reliability score fabricated for the occasion.
The Western loop described this week falsifies nothing. It assumes itself as industrial strategy. Hyundai does not lie about a performance figure: it openly claims to own everything, from the engine to the buyer. Humanoid.ai does not disguise any data: it publicly announces having secured more than half of its actuators until 2031. The lock has moved. It is no longer in the data, nor in the software brain: it is in the physical organ. We move from lying about performance to an assumed cold war of the actuator supply chain.
The list of five parallel questions one could ask this week — bipedal versus wheels, speed of cost reduction, credibility of a certain player, isolated AI milestones — was merely a backdrop. A single metric held the week, and the two Western camps have just locked it down on the same day: 60% of the cost is in the actuator. The robot is merely an assembly. The battle, however, is fought over the engine.